Subscribe:
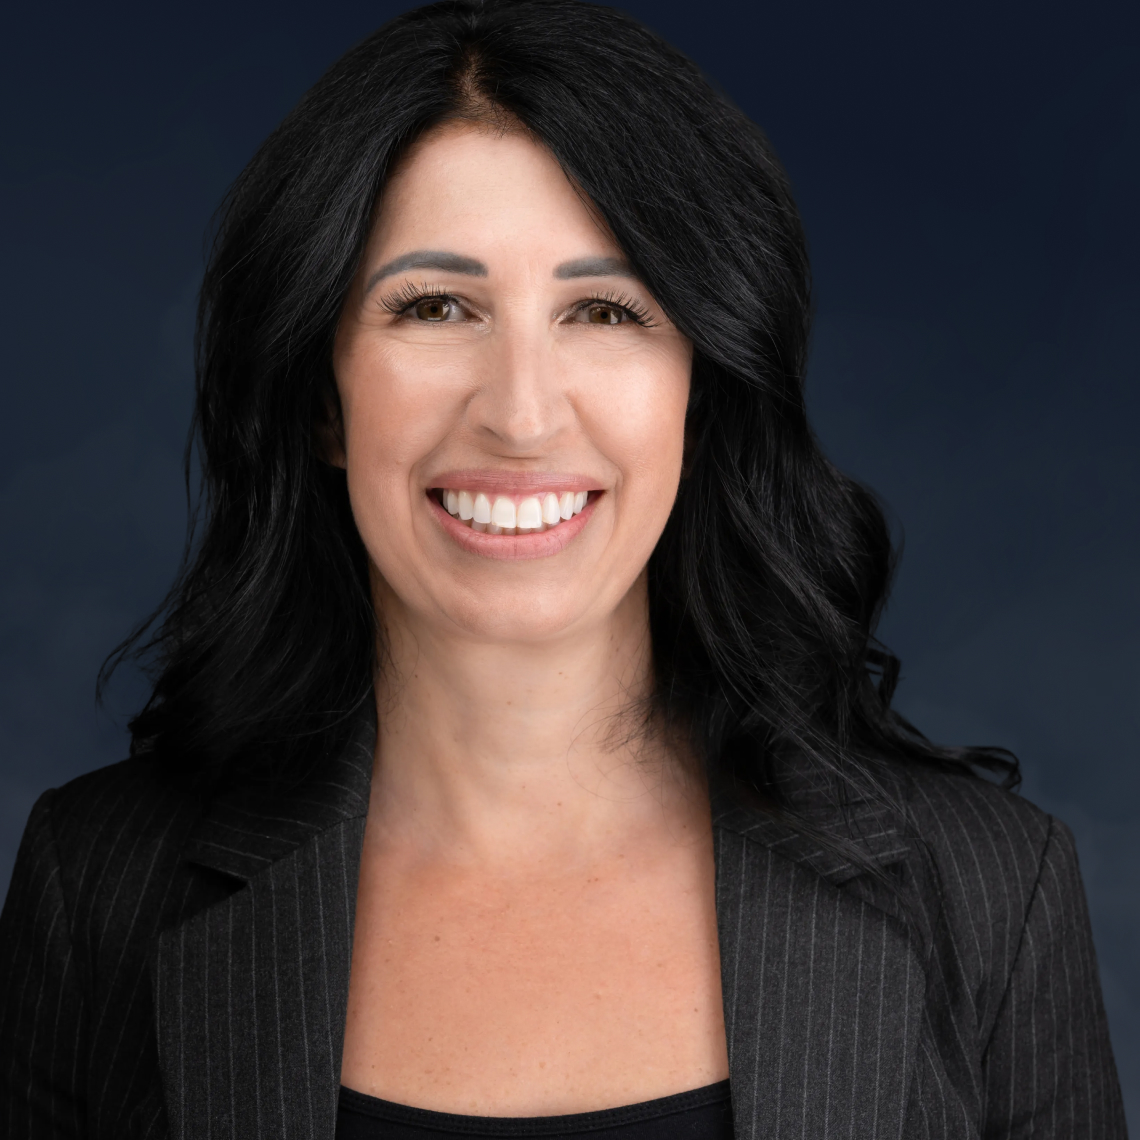
When a buyer asks one of Natalia Zacharin’s clients for their financials, her firm’s first job is to normalize and explain the numbers. The team sits down with the seller and goes through every transaction, separating the real cost of running the business from the owner’s personal and discretionary spending, so the buyer can see what the business would really earn under new ownership.
On Episode 319 of The Exit, host Steve McGarry talks with Zacharin, founder and CEO of accounting and fractional CFO firm Zacharin Consulting, about what buyers look for in a business’s numbers and operations, and why preparation should start years before a sale.

From a job in jeopardy to a fractional CFO firm
Zacharin did not plan to run a business. She was a single mother whose job was at risk when the person she had just started dating suggested she work for herself. She landed her first client in January 2019 with no real experience of building a company.
Today, she says, the firm has 17 employees, is a two-time Inc. 5000 honoree and is growing more than 100% year over year, with more clients asking for help to buy or sell.
What a buyer wants to see in your books
Buyers will typically look back three to five years, Zacharin says, and a savvy one wants month-by-month profit and loss statements, balance sheets and possibly cash flow statements to spot anomalies.
Her firm’s answer is a transparent recast. The team lists the owner’s personal and non-essential spending in a spreadsheet and adds it back, so the buyer can see what expenses and revenue would really look like under new ownership.
The add-backs need to be defensible. One client told her he planned to fly to a seminar by private jet rather than business class; a new owner might spend a fraction of that, or not go at all. The more of those expenses run through the business, the harder they are to explain, and the more the books start “looking a little bit fishy to the buyer.”
Pay yourself, and price in the people you will need
Mixing personal and business expenses is the first problem she looks for. The second is an owner who works in the business without paying themselves, which gives a buyer a false picture of what it costs to run. The owner should draw a reasonable wage for the role they actually perform; the owner of a $1 million company, she suggests, is probably not doing a half-million-dollar CEO job.
The same goes for missing staff. Zacharin describes an accounting firm for sale that had lost its manager a year earlier and was making do. A buyer would need that manager, so the salary had to be added back in, reducing profit.
She also flags tax strategies that reduce reported profit, which should be real and documented, and debt. Borrowing to make payroll is a warning sign, while debt for equipment that helps the business grow is, in her view, “sellable debt.” Either way, debt payments should not exceed profit.
Replace yourself before a buyer has to
Owners are often doing 50 different things, Zacharin says, and it can take five hires to replace them. The sooner those roles are filled, the more obvious it becomes to a buyer that the business is “plug and play,” and the more accurately the salaries show up in the profit figures.
McGarry compares founder dependency to customer concentration, calling it a risk almost as big as earning 90% of revenue from one customer. Zacharin is blunt about the consequence: if you do everything, “you’re just gonna sell and they’re gonna ask you to stay, now you’re gonna be an employee. That’s no fun.”
Part of stepping back is writing things down: documented SOPs for every process and workflow, so a new employee or owner can walk in and start working.
Why clean books can change a valuation
Zacharin’s sharpest example involves a franchise. Her firm kept the books for two of the five locations a buyer wanted to acquire; three other owners used different bookkeepers. She says the buyer valued her client’s business at 11x (“I guess, EBITDA,” she adds) and the others at only 2x, even though the businesses were of similar size. In her account, the difference was that the other owners’ books were not clean and had not been through the exercise of separating out owner benefits.
The episode does not say what else the buyer weighed, so the gap shouldn’t be put down to bookkeeping alone. Zacharin presents it as evidence that accurate financials are worth paying for.
She applies the same scrutiny to costs: unproductive staff, unused software seats and duplicate tools should go, because everything should generate revenue or support generating it.
How early to start and when to sell
Zacharin recommends at least three years of preparation, ideally with an outside advisor who can show which levers matter most and who is not emotionally invested; owners, she says, tend to think their business is worth more than it is. She also believes a business should think about its exit from day one, because building as if you might sell makes it stronger either way.
On timing, she weighs growth against market risk, citing Blockbuster and a story from John Warrillow’s The Art of Selling Your Business about an owner who turned down an offer and, two years later, had a business worth almost nothing. Her expectations are modest: selling a solid business for two to five times EBITDA or one to three times revenue is, in her view, doing pretty well. “There really isn’t any perfect moment.”
Building a business someone else can run
Most of Zacharin’s advice comes back to the same test: could a buyer see exactly what the business earns, and could it run without its owner? Ten years ago, she says, she was earning $7 an hour; owning a business has been the hardest thing she has done, and it showed her there is “no ceiling.” Find her firm’s resources for The Exit listeners at zacharinconsulting.com/theexit, connect with her on LinkedIn, or follow Zacharin Consulting on Instagram.